Texas Ag Exemption Explained 2026: Open-Space Productivity Appraisal, Not a Free Pass
Texas's "ag exemption" is usually 1-d-1 open-space productivity appraisal—not a homestead-style free pass. Qualifying use, April 30 deadline, wildlife option, and 3-year rollback.
Key Takeaways:
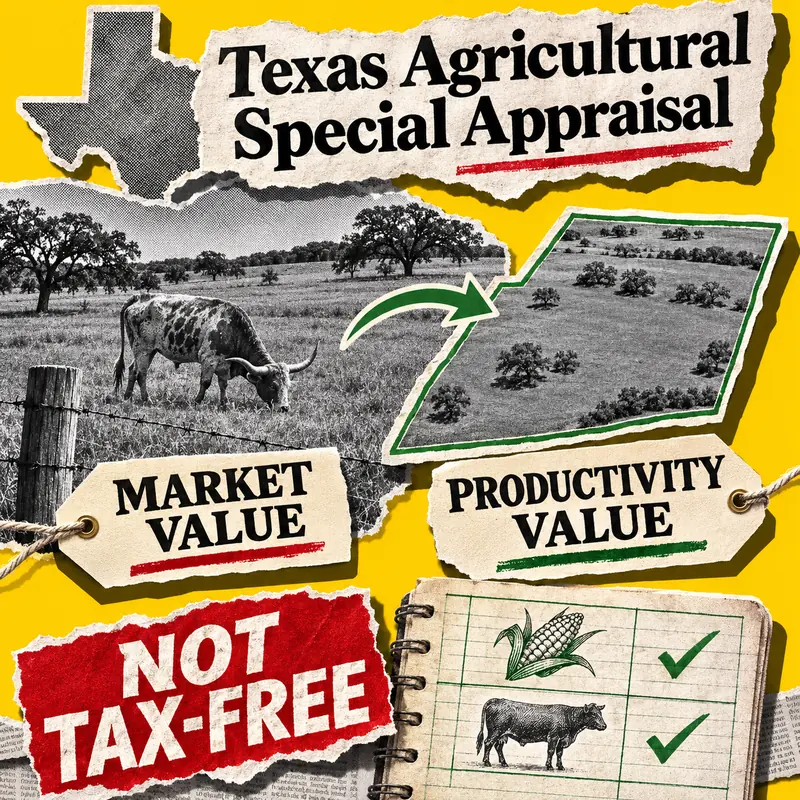
- Usually 1-d-1 open-space productivity appraisal—not a homestead-style exemption that zeros tax.
- Qualify with principal ag use at local intensity; generally 5 of prior 7 years; apply by April 30.
- Change of use can trigger a 3-year rollback (Tax Code §23.55); CAD sets intensity standards.
Last updated: Nov. 5, 2026
Texas's so-called "ag exemption" is usually not a homestead-style exemption that zeros out property tax. For most qualifying farm and ranch land, it is a 1-d-1 open-space special appraisal: the land is taxed on its agricultural productivity value instead of full market value. Productivity value is usually lower than market value, which is why the nickname stuck—but the tax does not go to zero, and the rules are set in Tax Code Chapter 23 and by your local appraisal district.
Debate after the Nov. 3, 2026 election revived calls to "end the ag exemption." This article is a plain explainer for owners and searchers. It does not take a political position on changing the law. It covers what qualifies, wildlife management, the April 30 application deadline, change-of-use rollback, and how this differs from protesting the market value of a house.
What is the Texas ag exemption, really?
The Texas Comptroller's agricultural, timberland and wildlife management page explains that the Texas Constitution and Tax Code allow certain farm and ranch land to be appraised on the land's capacity to produce agricultural products (productivity value) instead of market value. That special appraisal is commonly called an "ag exemption," but it is a valuation method, not an exemption that removes the property from the tax roll the way a residence homestead exemption reduces taxable value on a home.
Two related tracks exist in Chapter 23:
- 1-d-1 open-space (most common today). Tax Code §§23.51–23.57. Application is Comptroller Form 50-129.
- 1-d agricultural appraisal (older, narrower path). Application is Form 50-165. Different eligibility and rollback rules can apply.
Timberland and wildlife management also use special appraisal frameworks under Chapter 23. Always confirm which category your CAD approved on your account.
What land qualifies for 1-d-1 open-space appraisal?
Per the Comptroller, property owners may qualify if the land meets criteria that include:
- Principal agricultural use currently devoted to agriculture (cultivating soil, producing crops, raising or keeping livestock, poultry or fish, cover crops, certain exotic animals for commercial products, and related uses described in the statute and manuals).
- Degree of intensity generally accepted for the area. Your local CAD sets intensity standards; there is no single statewide acreage minimum that replaces those local guidelines.
- History: generally devoted to agricultural or timber production for at least five of the past seven years. Land inside an incorporated city or town must also meet extra criteria listed by the Comptroller.
Do not invent a statewide acreage threshold. Ask your CAD's agricultural appraisal guidelines or agricultural appraisal advisory board materials for the intensity standards that apply where you own land. For a local FAQ example, see Bexar CAD's agriculture / wildlife / rollback FAQ.
Does wildlife management count as agricultural use?
Yes, when the land meets the wildlife-management rules. The Comptroller states that using land for wildlife management is an agricultural use if the land was previously qualified open-space land or timberland and is actively used for wildlife management. Wildlife management land must be used in at least three of seven specific ways to propagate a sustaining breeding, migrating or wintering population of indigenous wild animals for human use. A wildlife management plan (Texas Parks and Wildlife Department forms) is typically required. See the Comptroller's Guidelines for Qualification of Agricultural Land in Wildlife Management Use and Tax Code §23.521.
When is the application deadline?
Applications for 1-d-1 open-space and related special appraisals are generally due by April 30 (Comptroller property tax law deadlines; Tax Code §§23.43, 23.54 and related sections). If April 30 falls on a weekend or holiday, Tax Code §1.06 rolls the act to the next regular business day. File with the appraisal district that appraises the land—not the tax office that mails the bill.
Late or incomplete applications can mean the land stays at market value for that year. Confirm forms (50-129 for 1-d-1 open-space) and any CAD addenda before the deadline.
What is change-of-use rollback?
If land receiving agricultural special appraisal changes to a non-agricultural use, the owner who changes the use generally owes a rollback tax. For 1-d-1 open-space land, Tax Code §23.55 provides that the rollback covers each of the previous three years in which the land received the lower appraisal. The rollback is the difference between taxes paid on the agricultural value and taxes that would have been paid on the higher market value. Additional interest rules can apply for some 1-d (Subchapter C) situations.
Exceptions exist for certain right-of-way sales, condemnations, public-purpose transfers and other listed cases—read §23.55 and ask your CAD before you change use, subdivide or develop. Bexar CAD's FAQ notes owners must notify the CAD in writing of a use change (timing rules apply).
How is this different from protesting a house's market value?
Open-space appraisal and a market-value protest are different tools:
- Ag / open-space: You apply for a special appraisal category. Qualification turns on use, intensity and history. If approved, the CAD appraises productivity value under Chapter 23.
- Homestead / residential protest: You protest the appraised (usually market) value or unequal appraisal at an informal review or ARB hearing under Tax Code Chapter 41. Evidence often includes comparable sales, condition and equity.
You cannot "protest" your way into ag appraisal at the ARB the same way you protest a house value; you apply for the special appraisal and, if denied, follow the CAD/ARB protest path for that determination. Separately, every Texas owner can still protest market value on improvements or on land that is not under special appraisal.
The usual protest deadline is May 15; in 2027 that falls on a Saturday, so it is generally Monday, May 17, 2027, or 30 days after your notice is delivered, whichever is later. You can file yourself or protest with TaxDrop. Here's how a Texas property tax consultant works. For local protest steps, see guides such as Bexar County property tax protest or your county page.
Sources: Texas Comptroller — Agricultural, timberland and wildlife management use special appraisal; Texas Comptroller — Property tax law deadlines; Texas Tax Code Chapter 23 (§§23.51–23.57, §23.55 rollback, §23.521 wildlife); Bexar CAD — Agriculture / wildlife / rollback FAQ; Texas Tax Code §§1.06, 41.44.
Paying Too Much in Property Taxes?
Let our licensed property tax experts assess your tax bill for potential savings. 92% of Texas protests we closed in 2026 got a reduction. It takes less than 3 minutes to enroll.
⏰
🏠
💵
No Savings No Fee
FAQs
Is the Texas ag exemption a free pass from property tax?
No. The common "ag exemption" is usually 1-d-1 open-space special appraisal: land is taxed on agricultural productivity value, which is usually lower than market value, but the tax does not go to zero.
What qualifies land for Texas 1-d-1 open-space appraisal?
Land must be devoted principally to agricultural use at the degree of intensity typical for the area, and generally must have been devoted to agricultural or timber production for at least five of the past seven years. Local CAD intensity standards apply; there is no single statewide acreage rule.
When is the Texas ag / open-space application due?
Applications are generally due by April 30. If that date falls on a weekend or holiday, Tax Code §1.06 rolls the deadline to the next business day. File with your appraisal district.
What is Texas ag appraisal rollback?
If land receiving 1-d-1 open-space appraisal changes to a non-agricultural use, Tax Code §23.55 generally imposes a three-year rollback equal to the difference between taxes paid on agricultural value and taxes that would have been paid on market value.
Can I protest market value instead of applying for ag appraisal?
Ag appraisal is a special-appraisal application under Chapter 23. A market-value protest under Chapter 41 is a separate process for appraised value or unequal appraisal. You cannot protest a tax rate at the ARB. The 2027 protest deadline is generally Monday, May 17, 2027, or 30 days after notice delivery, whichever is later.
Ryder Meehan
Ryder Meehan is the Co-Founder of TaxDrop and a Licensed Property Tax Protest Consultant


